Introduction
The Canned Vegetable Market is evolving as consumers, foodservice operators, retailers, and food manufacturers seek convenient, affordable, and shelf-stable food options. Canned vegetables provide a practical solution for households that want longer-lasting ingredients without the need for extensive preparation or frequent grocery shopping. Their extended shelf life also makes them useful for emergency food supplies, institutional kitchens, restaurants, and processed food manufacturing.
Canning technology enables vegetables to be preserved through controlled heat processing and sealed packaging. This process helps protect products from microbial deterioration while maintaining usability over extended periods. Depending on the vegetable, processing method, packaging medium, and storage conditions, canned products can offer different textures, flavors, and nutritional profiles.
Market analysis indicates that demand is influenced by changing lifestyles, food affordability, retail distribution, agricultural production, packaging innovation, and consumer preferences. At the same time, manufacturers face competition from frozen, fresh, dried, and minimally processed alternatives.
Market Structure and Product Landscape
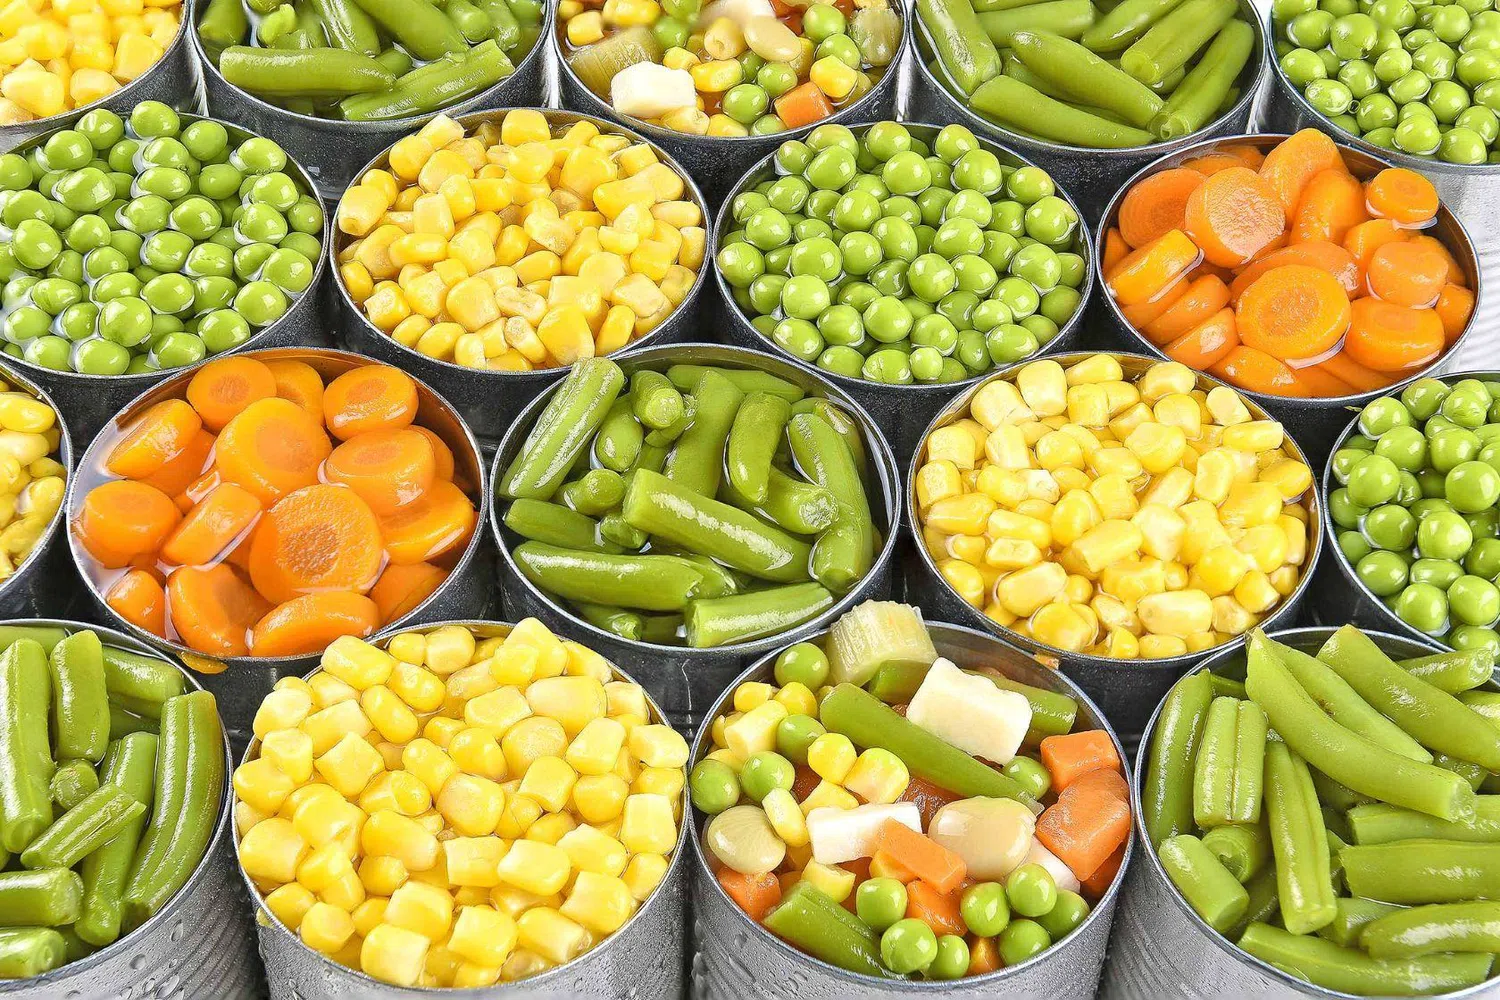
The Canned Vegetable Market includes a broad range of products such as sweet corn, peas, green beans, carrots, tomatoes, mushrooms, mixed vegetables, asparagus, potatoes, spinach, and other processed vegetables. Products may be sold individually or in combinations designed for specific meal applications.
Vegetables can be packed in water, brine, sauces, or other liquid preparations. Product formulations vary according to regional preferences and intended applications. Some products are designed primarily for household cooking, while others target foodservice and industrial users.
Packaging formats also contribute to market segmentation. Traditional metal cans remain widely used because of their durability, stackability, and strong barrier properties. However, manufacturers are increasingly evaluating alternative packaging formats that provide convenience, easier opening, improved portability, and potentially lower material usage.
Demand Analysis
Convenience is one of the strongest factors supporting demand. Modern households often prioritize products that reduce preparation time. Canned vegetables can be opened and incorporated directly into soups, stews, casseroles, salads, sauces, pasta dishes, and side dishes.
The products are particularly useful when fresh vegetables are unavailable, expensive, or inconvenient to store. Their relatively long shelf life reduces the pressure to consume products immediately after purchase, which can be attractive for consumers managing household food inventories.
Foodservice demand is another important component. Restaurants, cafeterias, catering businesses, hotels, schools, hospitals, and institutional kitchens can use canned vegetables as standardized ingredients. Their predictable availability can simplify inventory planning and reduce preparation requirements.
Consumer Behavior and Purchasing Patterns
Consumers increasingly consider several factors when purchasing canned vegetables, including price, convenience, package size, ingredient composition, sodium content, nutritional characteristics, brand reputation, and product versatility.
Price sensitivity is particularly important because canned vegetables are frequently positioned as economical pantry products. During periods of elevated food costs, consumers may adjust purchasing patterns toward products with longer shelf lives and lower costs per serving.
At the same time, some consumers are moving toward products perceived as healthier or less processed. This creates opportunities for low-sodium, no-added-salt, organic, preservative-free, and clean-label product variations where commercially and technically feasible.
Package size also influences purchasing behavior. Smaller cans can appeal to individuals and smaller households, while larger formats are useful for families, foodservice operations, and institutional consumers.
Retail Distribution Analysis
Supermarkets and hypermarkets remain important channels because they provide extensive shelf space and allow consumers to compare different brands, varieties, and package sizes. Grocery retailers can also promote canned vegetables through discounts, multipack offers, and private-label products.
Convenience stores have a more limited assortment but can benefit from demand for practical pantry products. Wholesale and club-based retailers can support larger package sizes and multipack purchasing.
E-commerce is becoming increasingly relevant to the Canned Vegetable Market. Online grocery platforms allow consumers to search for specific varieties, compare prices, read product information, and purchase products in bulk. Digital distribution can also help manufacturers reach consumers beyond traditional retail footprints.
Regional Market Dynamics
Market conditions vary considerably by region because vegetable consumption habits, agricultural production, income levels, retail structures, and culinary traditions differ.
Developed markets generally benefit from established packaged-food distribution networks and strong supermarket penetration. Consumers in these markets may show greater interest in specialized products such as organic vegetables, low-sodium formulations, premium varieties, and convenient packaging.
Emerging markets can provide opportunities through urbanization, expanding modern retail infrastructure, rising disposable incomes, and changing household lifestyles. However, price remains a major consideration, particularly where fresh vegetables are readily available through traditional markets.
Local cuisine also shapes demand. Vegetables commonly used in soups, curries, stews, pasta dishes, and mixed meals may experience stronger demand in particular markets.
Competitive Landscape
Competition in the Canned Vegetable Market exists across branded manufacturers, regional processors, private-label suppliers, and foodservice-oriented producers. Companies compete through product variety, pricing, distribution reach, packaging, quality consistency, and product positioning.
Private-label products can exert considerable pressure on branded manufacturers because retailers can offer lower-priced alternatives. This encourages established producers to differentiate through quality, specialized formulations, sustainability initiatives, packaging improvements, and recognizable product positioning.
Supply chain efficiency is also a significant competitive factor. Manufacturers must coordinate agricultural sourcing, processing facilities, packaging materials, transportation, warehousing, and retail distribution. Efficient operations can help reduce costs while maintaining consistent product quality.
Pricing and Cost Factors
Pricing is influenced by vegetable availability, agricultural yields, labor expenses, energy costs, packaging materials, transportation, storage, and processing capacity.
Agricultural variability can create cost pressure. Weather conditions, water availability, crop diseases, and changes in planting decisions can affect the supply and quality of vegetables available for processing.
Metal packaging costs are another consideration. Fluctuations in raw material prices can influence manufacturing expenses and ultimately affect retail pricing. Energy-intensive thermal processing and transportation costs can also influence profitability.
Manufacturers therefore increasingly focus on procurement planning, production efficiency, automation, inventory management, and supply chain optimization.
Technology and Processing Developments
Processing technology continues to influence product quality and manufacturing efficiency. Improvements in sorting, washing, cutting, filling, thermal processing, inspection, and packaging automation can increase production consistency while reducing waste.
Advanced quality-control systems can help manufacturers monitor package integrity, processing parameters, and product characteristics. Automation can also address labor shortages and improve throughput in large-scale processing facilities.
Research into improved processing techniques is focused on balancing food safety, shelf stability, texture, appearance, flavor, and nutritional retention. These considerations are increasingly important as consumers become more attentive to food quality.
Sustainability Considerations
Environmental considerations are becoming more important throughout the food packaging industry. Manufacturers are examining packaging material efficiency, recyclable components, energy consumption, water usage, transportation emissions, and agricultural waste.
Metal cans have established recycling infrastructure in many markets, which can support their sustainability positioning. However, manufacturers continue to face pressure to reduce material use and improve manufacturing efficiency.
Agricultural by-products and processing waste can also present opportunities. Depending on the vegetable and processing system, residual materials may be used for animal feed, composting, bio-based applications, or other secondary purposes.
Key Market Challenges
The market faces competition from fresh and frozen vegetables, which can appeal to consumers seeking specific textures, flavors, or nutritional characteristics. Refrigeration infrastructure and improved frozen-food distribution can further strengthen alternative product categories.
Health perceptions can also affect demand. Some consumers associate canned foods with higher sodium levels or extensive processing. Producers are responding through reformulation, clearer labeling, and the development of products designed around changing nutritional preferences.
Supply chain disruptions represent another challenge. Agricultural shortages, packaging constraints, transportation disruptions, and energy-price volatility can affect production costs and product availability.
Future Market Outlook
The future development of the Canned Vegetable Market is likely to depend on the interaction between affordability, convenience, health preferences, technological development, and sustainability.
Manufacturers are expected to continue expanding product variety while improving formulations and packaging formats. Low-sodium products, convenient portion sizes, premium vegetables, organic offerings, and products designed for specific meal occasions can create additional opportunities.
Digital grocery shopping is also likely to remain an important distribution channel. Better product visibility online can help manufacturers reach niche consumer groups and support direct engagement with buyers.
Overall, the Canned Vegetable Market remains an important component of the packaged-food industry because it combines convenience, storage stability, accessibility, and versatility. Companies that effectively manage agricultural sourcing, production efficiency, product quality, packaging innovation, and evolving consumer expectations will shape the market's future direction.